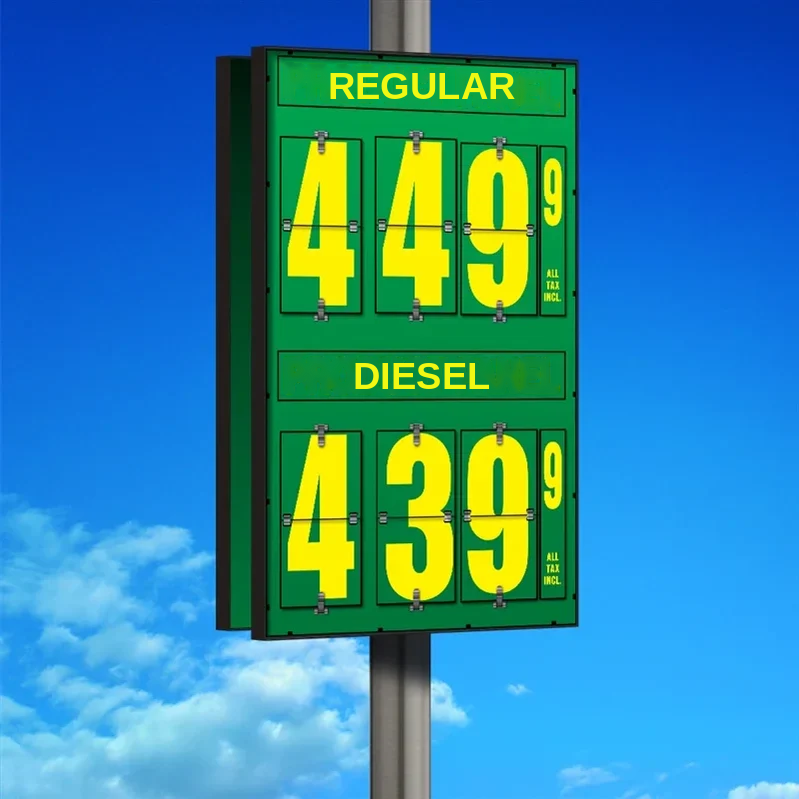
Credit departments today are managing customers whose fuel costs have jumped 50% or more, often without any change in gallons delivered. That means credit limits are stretched, aging buckets are swelling, and pastdue balances are creeping upward. The workload increases, the risk increases, and the margin for error shrinks. In times like these, your credit team needs more than vigilance — they need a strategic, disciplined playbook.
Below are Ateam strategies to help you navigate this volatile environment.
1. Build a “Top 10 Watch List” — Your Early Warning Radar
A wellmaintained watch list is one of the most powerful tools a credit department can use. It keeps management informed and prevents surprises.
Your watch list should include:
- Customers asking to delay drafts or restructure payments
- Highvolume accounts showing slower payment patterns
- Customers suddenly unavailable for collection calls
- Accounts with rising balances but inconsistent communication
- Customers whose purchasing behavior has changed abruptly
This list isn’t about customers already in the 90day bucket — it’s about identifying early distress signals before they become fullblown problems. Review it weekly. Share it with leadership. Treat it as your radar system.
2. Reevaluate Credit Limits with Today’s Pricing Reality
Credit limits set in the past may no longer make sense in a world where fuel prices have doubled. But this doesn’t mean you should overhaul your entire credit book.
Instead:
- Focus on the top 20% of customers who drive the majority of your volume
- Identify accounts already under scrutiny
- Adjust limits temporarily and revisit them as prices stabilize
- Document your rationale for each adjustment
This targeted approach keeps your workload manageable while protecting your exposure where it matters most.
3. Conduct Focused Credit Reviews on AtRisk Customers
A credit review is your chance to reassess the customer’s financial health with fresh eyes.
Your review should include:
- A new credit report
- A comparison of current payment habits vs. historical trends
- Updated financial statements
- A benchmark against your original credit analysis
- A review of industry conditions affecting the customer
Set a goal: five credit reviews per week. This keeps the process moving without overwhelming your staff.
4. Educate and Align Your Entire Team
In a volatile market, credit policy cannot operate in a silo. Everyone who touches the customer — sales, dispatch, customer service, warehouse staff, bulk plant personnel — must understand that it is not business as usual.
Train your team on:
- Why product release may require additional approval
- How credit limits may have changed
- What red flags to watch for in customer behavior
- How to escalate concerns quickly and accurately
Also consider scenarios like:
- A customer returning after years of inactivity
- Sudden large orders from historically small accounts
- Customers switching suppliers abruptly
These are often signs of distress, not opportunity. Your team must be equipped to recognize them.
The Bottom Line
Increasing credit department efficiency and tightening internal processes is always valuable — but during extreme pricing spikes, it becomes essential. Your Ateam must be aligned, proactive, and disciplined. By implementing the strategies above, you can protect your business, support your customers, and navigate volatility with confidence.